A bridge loan is short-term financing that lets you use the equity in your current house to buy the next one before the current one sells. Many Canton sellers never need one. It solves one specific problem: wanting to buy first, with a strong offer, without waiting on your own sale. Whether it makes sense for you depends on what it would cost in your case, how long you might carry it, and how it compares with the other ways to bridge the same gap, which a lender can lay out side by side before you commit to anything.
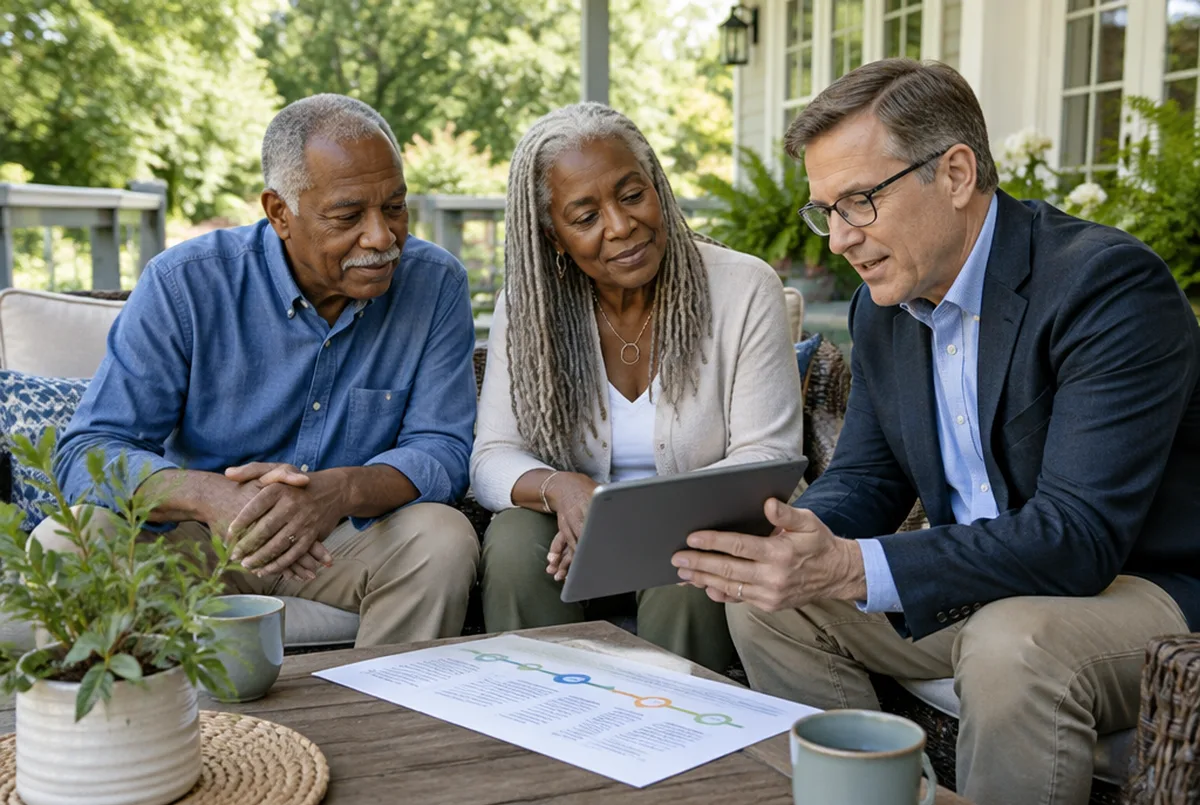
James and Elizabeth had been watching one street near downtown Canton for almost three years, waiting for a one-level house to come up. The names are fictional to protect my clients’ privacy. The situation is real. When it finally did, their own house was not listed, the guest room was still full of holiday decorations, and Elizabeth asked the question that brought them to my table: “Can we buy it before we sell ours?”
It is a stressful moment. The house you have been waiting for does not care about your timeline, and it can feel as if every option means either losing it or taking on a risk you do not fully understand. Understanding the risk is the part you can fix in an afternoon.
What exactly is a bridge loan?
It is a loan meant to cover a short window, secured by the house you already own. The money typically goes toward the down payment or the purchase of the next home, and the loan is repaid when your current house sells. It is a bridge in the most literal sense: something to stand on between two pieces of ground, not somewhere to live.
Like any loan, it has its own terms and its own costs, and those vary from lender to lender and case to case. That is why the specifics belong in a conversation with a lender who has looked at your situation, not in an article. What an article can do is help you walk into that conversation with the right questions.
What problem does it actually solve?
Two. The first is the strength of your offer. A purchase that depends on selling your current home asks the seller to wait on something they do not control, and where a home draws more than one offer, that can be the difference. Bridge financing can let you make an offer that does not carry that condition.
The second is the move itself. If you buy first, you can move once, settle in, and then prepare and sell the old house empty, without showing it around your daily life. For some sellers that alone is worth a great deal. For others, it is a convenience that does not justify the cost.
What does it cost besides the loan itself?
Time, mostly. While you own both homes, you carry both: property taxes, insurance, utilities and maintenance on the house you are no longer living in. Even when the old house is paid off, those continue. Property taxes in Cherokee County are a good place to start adding up the monthly figure.
There is also a quieter cost: a deadline. A bridge loan is designed to be repaid when the house sells, and the longer the sale takes, the more the arrangement costs and the more pressure you may feel to accept a lower offer. That makes the sale plan part of the financing plan. In August, homes that sold in Cherokee County had been on the market a median of 27 days, while those still waiting had been listed for 51, according to the Cherokee Association of Realtors. Above $600,000, sales tend to take longer. Here is why that happens and what changes it.
What are the alternatives?
There are several, and each fits a different situation. You can sell first and arrange a short stay in your house after closing while you buy. You can make an offer that depends on your sale, which can be more acceptable where homes take longer to sell. You can ask the seller of the next home for a longer closing date. And some homeowners use a line of credit on their current house, or savings and investments they already have.
Two cautions on those last ones. A line of credit has its own rules about when it can be opened, so ask a lender about timing before the house is listed, not after. And using savings or investments is a question for your CPA or financial advisor, because how and when you draw on them can matter at tax time. We can show you how each option affects the move; where your money should come from is their conversation.
How do I know if I need one?
Four questions usually answer it. How competitive is the home you want, and would a seller there wait on your sale? How ready is your current house, and how long is it likely to take at the right price? Could you live with a short rental or a stay after closing instead? And what would carrying both homes cost each month, for how many months, before it stopped feeling comfortable?
Ask the lender to put the bridge option and at least one alternative on a single page, with the total cost of each over a realistic timeline. You are free to choose any lender you like. When the comparison is on paper, the decision usually stops being a feeling and becomes a choice.
If you are weighing whether to sell before you buy in the first place, start there. A bridge loan is one answer to that question, not the question itself.
So what are my options?
You can use bridge financing if the next home truly cannot wait and the carrying cost fits comfortably. You can sell first with a stay after closing and accept a little less certainty about the next house. You can make a contingent offer where sellers have time to consider it. Or you can let this house go and be ready, house prepared and financing confirmed, for the next one that comes up.
James and Elizabeth asked for the one-page comparison that same week. Seeing both columns side by side, they knew within a day which risk they were willing to carry. The holiday decorations were the easy part.
When the right house shows up before you are ready, what would you want to already know?